
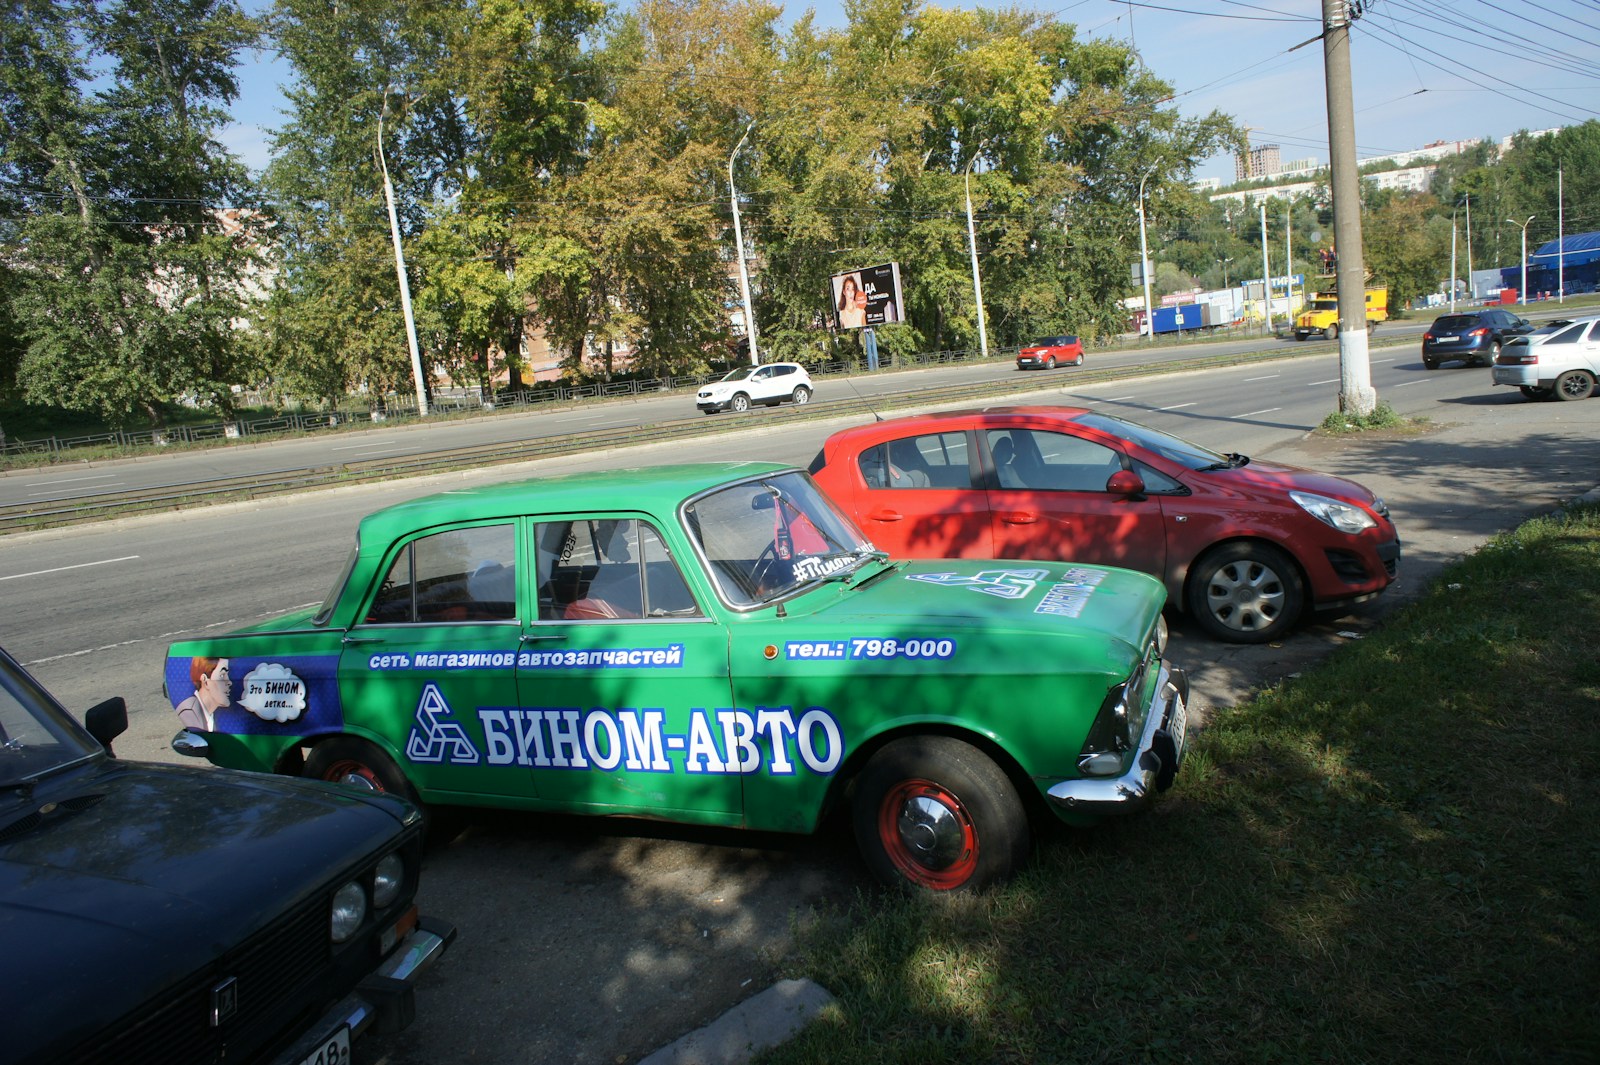

The pitch shows up in a text message, a job board listing, or a direct message on social media: wrap your car in a brand’s logo, drive your normal routes, collect a check every week for doing essentially nothing. Then a check arrives for far more than promised — often a couple thousand dollars instead of the couple hundred advertised — with instructions to deposit it, keep a slice as your first payment, and wire the rest to a “wrap installer” who will supposedly show up to apply the vinyl. The Federal Trade Commission has been documenting this exact scheme since at least 2016, and it is still circulating because the mechanics rarely change: the money looks real for just long enough to do damage.

How the check actually fails
The FTC’s own consumer alert lays out the sequence in plain terms: “They tell you to deposit the check, keep part of it as your share, and wire the rest to another company that will wrap your car.” Banks are required to make deposited funds available within a set number of days under federal rules, which is exactly what scammers exploit — the money shows up as “available” in an account long before the check has actually cleared. According to the FTC, “weeks after you wire the money, the check bounces and your bank tells you it was a fake.” By then the wired funds are gone, gone for good, sent through a wire transfer or a gift card purchase that cannot be reversed. The victim is not only out that money — the bank holds them responsible for the full amount of the bad check, since depositing it made them the one legally on the hook.
The FTC flags the logical hole that should tip people off before they ever wire a dime: “If this were a legitimate car wrap opportunity, wouldn’t the company directly pay the car-wrapping vendor, instead of asking you to do it?” No legitimate advertiser routes its own vendor payments through a random driver’s personal checking account. That single structural detail — a company that needs you to be the one moving its money to a third party — is the scam’s tell in nearly every version of it.
State regulators are tracking the same pattern
Massachusetts issued its own consumer alert after the Better Business Bureau flagged a wave of impersonation attempts using recognizable consumer brands — Monster Energy, Coca-Cola, Heineken, and 7UP names were all used without authorization to make the offers look credible. One case cited in that alert involved a victim told he could earn “$700 a week” to wrap his car with a 7UP logo — a specific, believable number, which is precisely the point. Scammers do not lead with implausible riches; they lead with numbers that sound like a decent side hustle, then let the fake check do the persuading. State-level alerts matter here because they show this isn’t an isolated incident the FTC caught once — it’s a durable pattern regulators in multiple jurisdictions have independently corroborated.
What legitimate car-wrap advertising looks like
Real vehicle-wrap advertising programs do exist, and drivers do get paid for them, but the process looks nothing like the scam version. A legitimate advertiser or its verified marketing agency pays the wrap installer directly — the driver is never asked to be the middleman moving funds to a vendor they’ve never met. There’s no unsolicited check for thousands of dollars more than the job is worth, and no urgency to wire money before a “deadline.” Any offer that starts with a check and ends with a wire transfer request should be treated as disqualifying on its own, regardless of how professional the branding looks.
Basic protections that hold up against this scam
- Never wire money or send gift cards based on funds from a check you just deposited — availability in your account balance is not the same as a check having cleared, which can take weeks to fail.
- Verify any advertising opportunity by contacting the named brand directly through its official website, not through a link or number provided in the offer itself.
- Be skeptical of any “employer” who overpays and asks you to return the difference — that pattern shows up across job scams, mystery shopper scams, and rental scams, not just car wraps.
- Report suspected scams to the FTC at ReportFraud.ftc.gov and to your state attorney general’s consumer protection office.
The car-wrap scam survives because it borrows the shape of something plausible — brands really do pay for vehicle advertising, and side income really is appealing. But the mechanism regulators keep documenting is consistent: a check that looks cleared but isn’t, a wire transfer that can’t be undone, and a bank that will come looking for its money weeks after the “opportunity” already vanished.