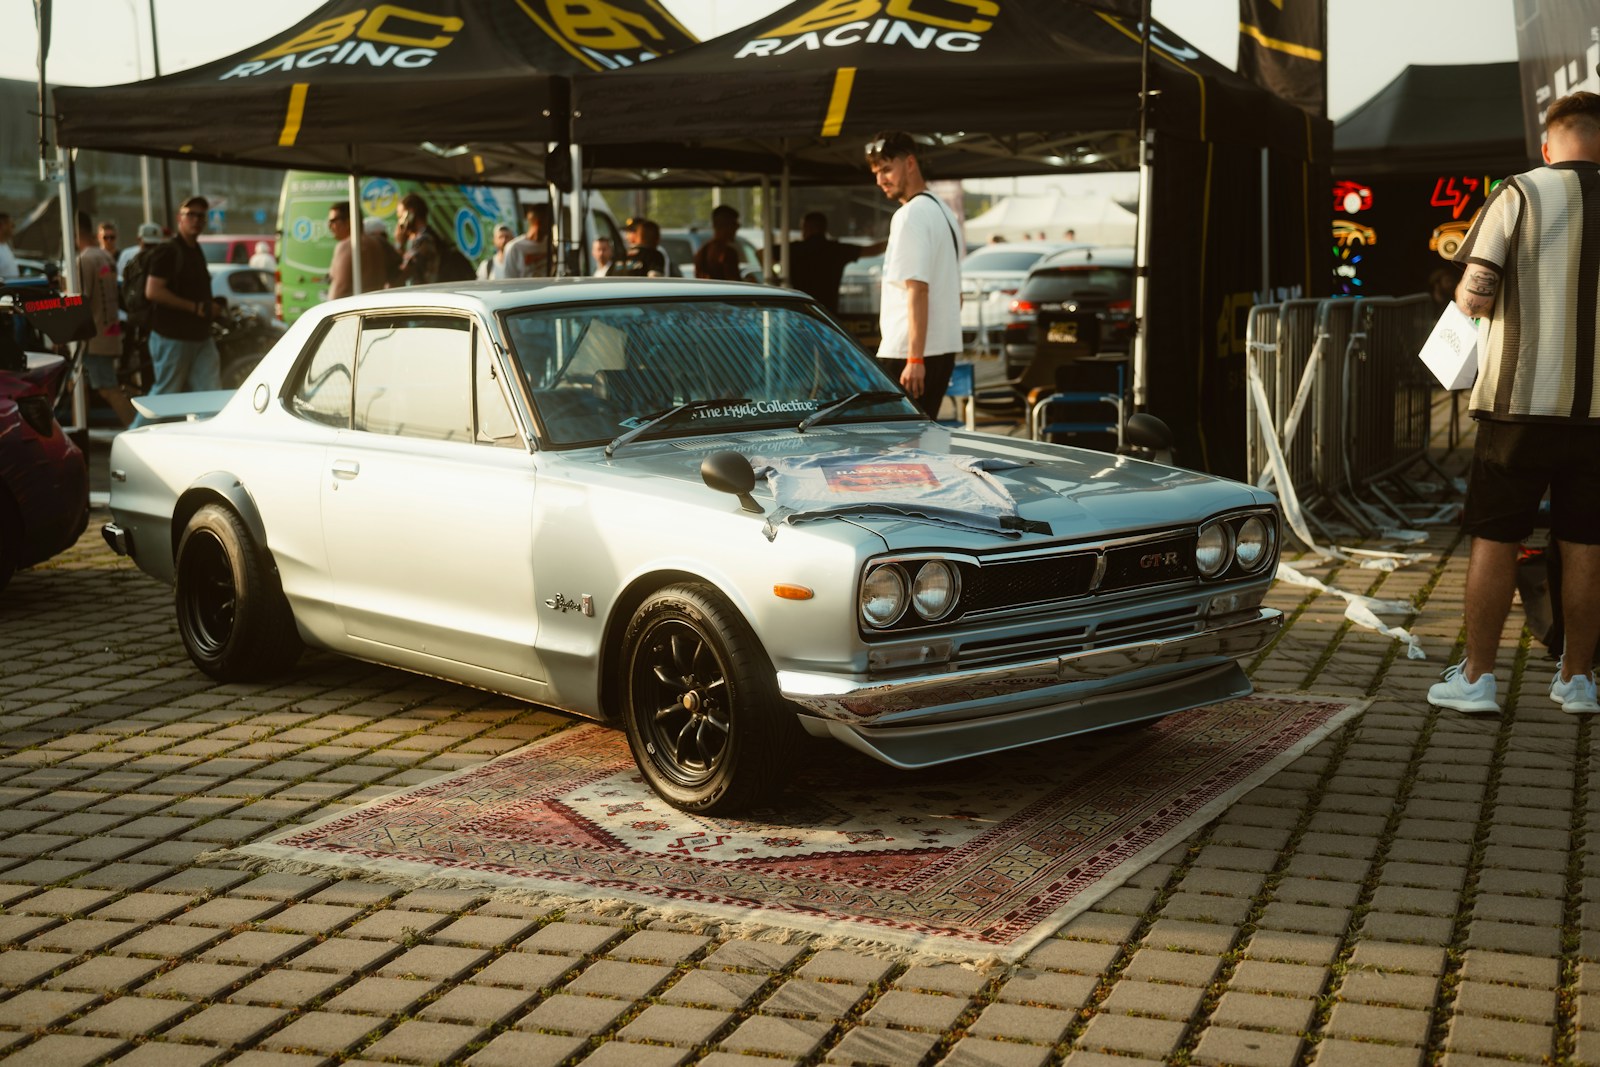

Nissan Skyline GT-R R32 values climbed from an average of $25,000 in September 2015 to $34,900 by May 2020, roughly a 30 percent gain in under five years, according to Hagerty’s own valuation team, and the best-condition R34 GT-R examples have reached $316,500. What’s changed the underwriting conversation more than the prices, though, is who’s buying: millennials now generate nearly 80 percent of Hagerty’s insurance quote requests for Skylines, compared with just a 20 percent millennial share of Hagerty’s overall insured vehicle portfolio. A specialty insurer that built its pricing models around older, longtime collectors is now writing policies for a completely different buyer on a car type its actuarial tables were never built for.
The 25-year rule is manufacturing an entirely new insurance category every year
Under U.S. import law, a foreign-market car becomes legal to bring in once it turns 25 years old, and Japan’s domestic market spent the late 1980s and 1990s producing exactly the kind of high-performance, right-hand-drive cars American enthusiasts wanted and couldn’t buy. The R32 GT-R crossed that threshold in 2014, and more than 1,900 examples have since entered the U.S.; the R33 has topped 2,200 imports and, according to Hagerty’s own tracking, already eclipsed the R32’s initial import surge; the R34 began trickling in as it approached its own eligibility date, with Hagerty’s team noting rising anticipation for the model well before its 25-year window fully opened. Every January 1st adds another model year’s worth of JDM cars to the pool insurers have to figure out how to price, which means this isn’t a one-time adjustment. It’s a rolling, permanent expansion of the market these companies underwrite.

Standard actuarial pricing doesn’t work on cars with no U.S. sales history
A Honda Accord has decades of claims data, parts pricing, and depreciation curves that a standard insurer can plug into a rate table. A federally imported Skyline never went through that process, because it was never sold here in period. That’s the specific problem specialty classic insurers are built to solve: rather than pricing off a depreciating book value, companies including Hagerty, Grundy, and American Collectors use an agreed-value or guaranteed-value model, where the owner and insurer settle on the car’s worth upfront and that figure pays out in full if the car is totaled, with no depreciation argument at claim time. It’s a fundamentally different pricing mechanism than the one covering your daily driver, and it exists specifically because standard insurers struggle to value rare JDM imports at all.
The underwriting requirements are doing the work rate tables can’t
Because there’s no claims history to lean on, these policies lean instead on behavioral guardrails: garage storage requirements, a separate daily-driver vehicle on file, limited annual mileage, and a clean driving record are standard conditions across specialty JDM coverage, the same basic framework these insurers have long used for domestic muscle cars and prewar classics, now extended to a category of vehicle none of them were writing policies on a decade ago. Those terms are effectively a substitute for the actuarial data a mainstream insurer would otherwise use. If the company can’t statistically model how often this specific car gets driven into a guardrail, it instead structures the policy so the car mostly isn’t being driven into guardrails in the first place.
A younger buyer base is testing that model in real time
The millennial skew in Skyline quote volume matters because the agreed-value model was built with an assumption baked in: that collector-car buyers are older, more experienced drivers who store their cars and drive them sparingly. An 80 percent millennial share of quote requests, against a 20 percent share of the overall book, means insurers are now writing that same policy structure for a buyer profile the model wasn’t originally built around, and the mileage caps, storage requirements, and daily-driver stipulations are precisely the levers being used to keep the risk profile intact regardless of the buyer’s age.
The 25-year rule was written as an emissions and safety exemption, not an insurance policy, but it’s functioning as a pipeline that hands classic insurers a fresh, unpriced category of vehicle every single year. The companies that figure out how to underwrite a Skyline, an R33, and whatever clears the bar next January aren’t just reacting to a JDM boom. They’re building the actuarial playbook for a segment that didn’t exist a decade ago and keeps growing on a fixed annual schedule.