

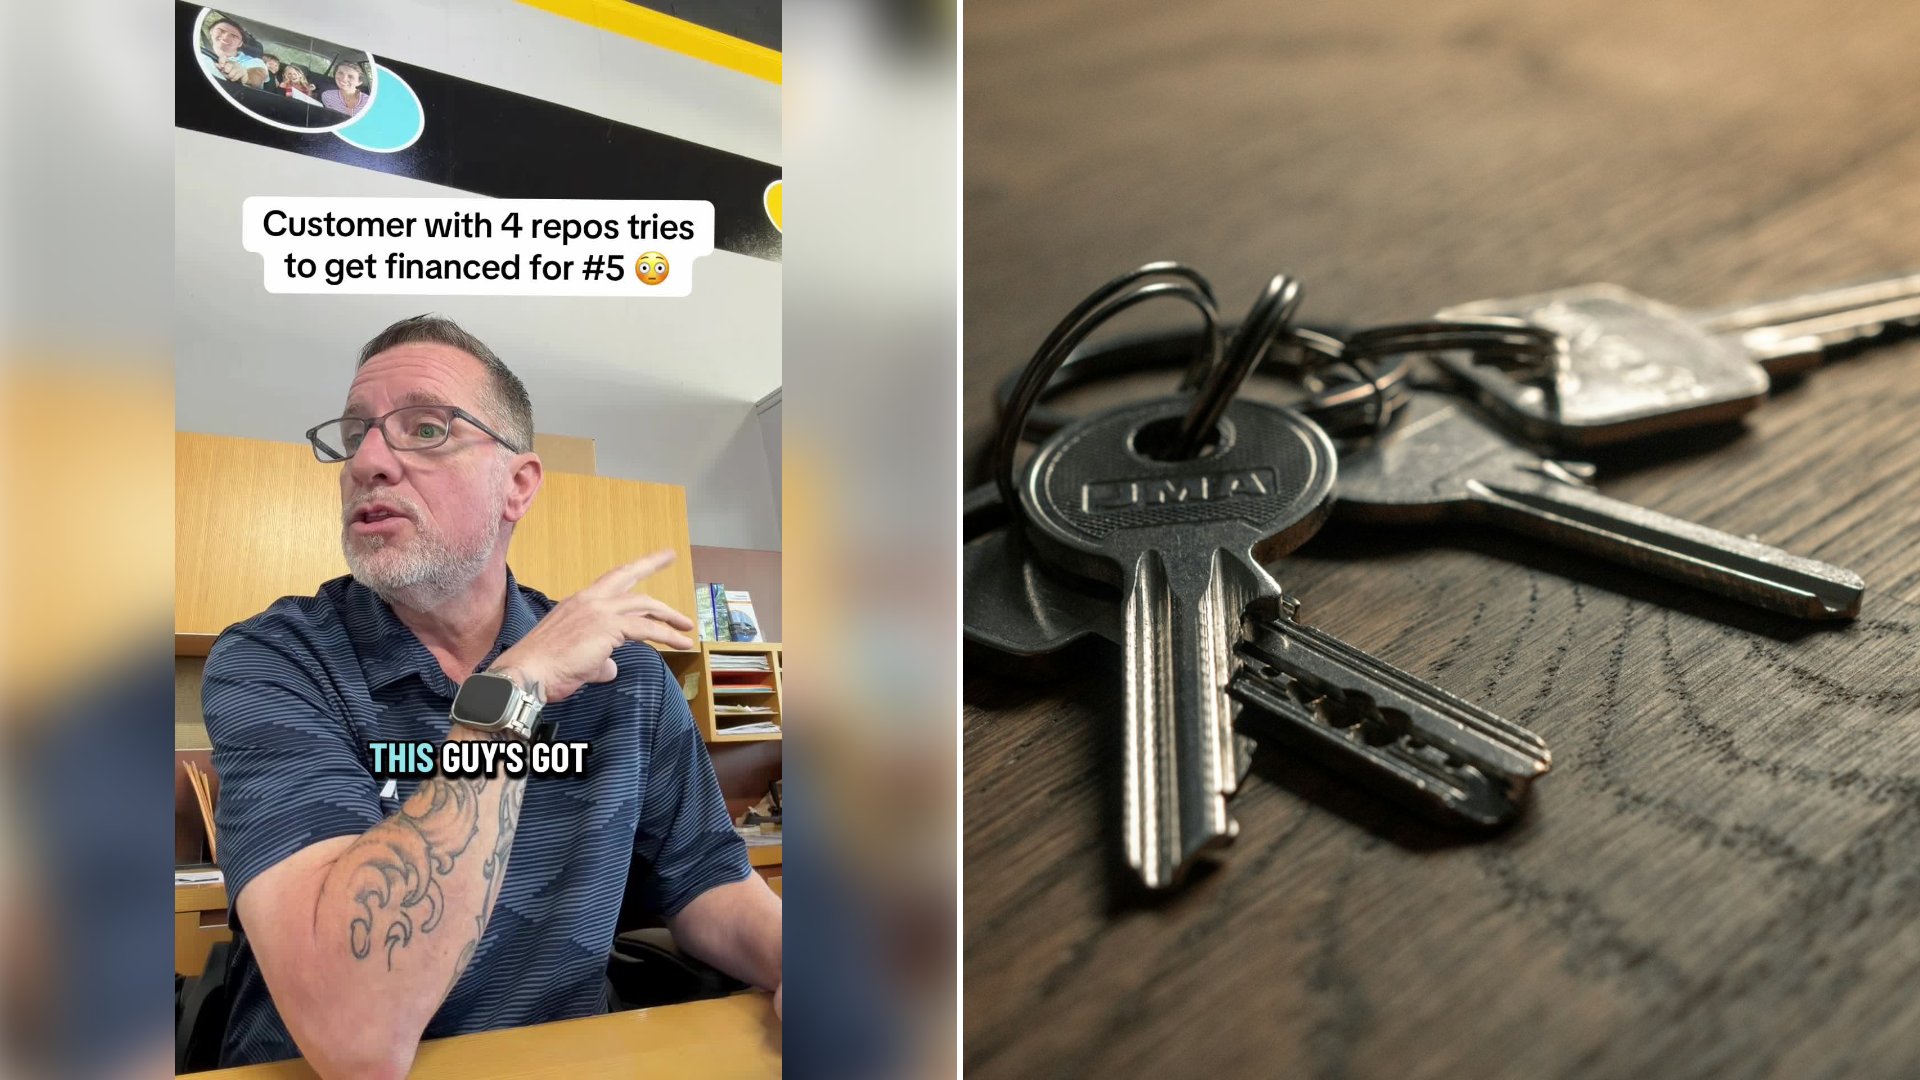
“This guy’s got 4 repos.” That is how a car salesman who posts as @goatforreal216 opens a 37 second clip filmed at his desk, reading out the file of a credit applicant who wants to finance one more vehicle. The on screen text sums it up: “Customer with 4 repos tries to get financed for #5.”
He sits at a wooden desk in a striped polo, turning to talk to someone off camera, and runs through the numbers as he reads them. “He’s a 479,” he says. “He’s past due on current bills, $46,000.” The caption is three words long: “I’m good thanks.”
Four repossessions in one file
According to his reading of the file, the applicant’s four repossessions are spread across several auto lenders, with two of them at the same credit union. He holds up two fingers for the pair at the credit union, then says it plainly: “He’s consistent. 4 repossessions.”
“I don’t wanna be number 5”
The decision takes seconds. “And he wants to try to get financed for another one,” he says. “I don’t wanna be number 5. Do you?” The reply is no, and he gives the instruction for the callback: “Call this guy back and say, we talked about it, and we decided we didn’t wanna be number 5.”
He closes with his own read on the deal: “There’s no doubt this guy is a repo waiting to happen. Whoever puts this guy in a car better have the tow truck on standby.” That is his view of this one applicant; the clip does not show the callback or say whether any other lender approved him.
What a repossession does to a credit file
The 479 he reads out sits near the bottom of the range. Experian notes in its guide to the scores used for car loans that many scoring models run from 300 to 850, while FICO’s auto industry scores run from 250 to 900, and that the best rates and offers may need a score in the mid to high 700s or above.
Each repossession stays on the record for a long time. According to Experian, a repossession remains on a credit report for seven years, and the countdown starts from the date of the first missed payment that led to it, not the date the car was taken. Experian adds that a repossession can make it difficult to qualify for new credit, and that borrowers who do qualify can face higher rates and fees.
Lenders are also seeing more late payments across the market. The Federal Reserve Bank of New York’s household debt report for the second quarter of 2026 put auto loan balances at $1.71 trillion and found that 3.00 percent of auto loan balances were transitioning into serious delinquency of 90 days or more, up from 2.93 percent a year earlier, with new auto delinquencies described as remaining “at elevated levels.”
What happens after a repossession
A repossession does not always end the debt. The Federal Trade Commission explains in its vehicle repossession guidance that in many states a lender can take a car as soon as the borrower defaults, without notice, as long as it does not “breach the peace.” The lender can keep the car or sell it at a public auction or private sale. If the sale brings in less than the borrower owes plus certain expenses, the gap is called a deficiency, and in most states the lender can sue for a deficiency judgment. If the sale brings in more, the surplus may have to be returned to the borrower.
If a repossession is already on your record
Pull your credit reports before you shop. Check the date of the first missed payment on each repossession, because that is the date Experian says the seven year clock runs from.
Ask about any deficiency before you apply. If a lender sold a repossessed car for less than you owed, find out the balance and whether a judgment was filed, since an unpaid balance will be in the file the dealer reads.
Know your rights if a car is taken. The FTC says some states let you buy the car back by paying the full amount owed plus repossession costs, some allow reinstatement by paying the past due amount and expenses, and a lender cannot keep or sell personal property found inside the car until a period set by state law has passed. Your state attorney general or local consumer protection office can tell you which rules apply.
Bring past due accounts current first. The first numbers the salesman read out were the score and the $46,000 in past due bills, and Experian’s score guide notes that a higher score indicates a borrower is less likely to miss a loan payment.